Latest Letter
Insights
How we think through markets — letters, webinars, perspectives and everything in between. The same reasoning that drives our portfolio decisions.
Long & Short
Deep-form articles and short contrarian takes.
Data Stats
One chart. One idea. Market insights the numbers reveal.
Time Machine
Historical market moments revisited — what we thought then, and now.
Time Machine
The box that changed the world
Time Machine
The dinner that changed how we pay
Time Machine
The banker who saw value in the rubble
Time Machine
The Number that was never meant to predict a crisis
Long Webinars
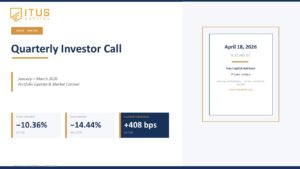
Full investor calls and market discussions — uncut, unscripted, quarterly.




Bytes
Short-form clips cut from full webinars, plus standalone takes on specific market moments.
Byte ·
1 min read
ITUS 3Q Investor Call Highlights 2025 – Snippet 10
Byte ·
1 min read
ITUS 3Q Investor Call Highlights 2025 – Snippet 9
Byte ·
1 min read
ITUS 3Q Investor Call Highlights 2025 – Snippet 8
Byte ·
1 min read
ITUS 3Q Investor Call Highlights 2025 – Snippet 7
Byte ·
1 min read
ITUS 3Q Investor Call Highlights 2025 – Snippet 6
Byte ·
1 min read
ITUS 3Q Investor Call Highlights 2025 – Snippet 5
Byte ·
1 min read
ITUS 3Q Investor Call Highlights 2025 – Snippet 4
Byte ·
1 min read
ITUS 3Q Investor Call Highlights 2025 – Snippet 3
Byte ·
1 min read
ITUS 3Q Investor Call Highlights 2025 – Snippet 2
Byte ·
1 min read
ITUS 3Q Investor Call Highlights 2025 – Snippet 1
Byte ·
1 min read
ITUS 2Q Investor Call Highlights 2025 – Snippet 4
Byte ·
1 min read
ITUS 2Q Investor Call Highlights 2025 – Snippet 3
Byte ·
1 min read
ITUS 2Q Investor Call Highlights 2025 – Snippet 2
Byte ·
1 min read
ITUS 2Q Investor Call Highlights 2025 – Snippet 1
Byte ·
3 min read
Itus Capital 2Q Investor Call 2025
Byte ·
1 min read
ITUS 1Q Investor Call Highlights 2025 – Snippet 5
Byte ·
1 min read
ITUS 1Q Investor Call Highlights 2025 – Snippet 4
Byte ·
1 min read
ITUS 1Q Investor Call Highlights 2025 – Snippet 3
Byte ·
1 min read
ITUS 1Q Investor Call Highlights 2025 – Snippet 2
Byte ·
1 min read
ITUS 1Q Investor Call Highlights 2025 – Snippet 1
Byte ·
1 min read
ITUS Annual Investor Call Highlights 2024 – Snippet 5
Byte ·
1 min read
ITUS Annual Investor Call Highlights 2024 – Snippet 4
Byte ·
1 min read
ITUS Annual Investor Call Highlights 2024 – Snippet 3
Byte ·
1 min read
ITUS Annual Investor Call Highlights 2024 – Snippet 2
Byte ·
1 min read
ITUS Annual Investor Call Highlights 2024 – Snippet 1
Byte ·
1 min read
ITUS 3Q Investor Call Highlights 2024 – Snippet 3
Byte ·
1 min read
ITUS 3Q Investor Call Highlights 2024 – Snippet 2
Byte ·
1 min read
ITUS 3Q Investor Call Highlights 2024 – Snippet 1
Byte ·
1 min read
ITUS 2Q Investor Call Highlights 2024 – Snippet 3
Byte ·
1 min read
ITUS 2Q Investor Call Highlights 2024 – Snippet 2
Byte ·
1 min read
ITUS 2Q Investor Call Highlights 2024 – Snippet 1
Byte ·
1 min read
ITUS 1Q Investor Call Highlights 2024 – Snippet 3
Byte ·
1 min read
ITUS 1Q Investor Call Highlights 2024 – Snippet 2
Byte ·
1 min read
ITUS 1Q Investor Call Highlights 2024 – Snippet 1
Byte ·
1 min read
ITUS Annual Investor Call Highlights 2023 – Snippet 3
Byte ·
1 min read
ITUS Annual Investor Call Highlights 2023 – Snippet 2
Byte ·
1 min read
ITUS Annual Investor Call Highlights 2023 – Snippet 1
Byte ·
1 min read
ITUS 3Q Investor Call Highlights 2023 – Snippet 3
Byte ·
1 min read
ITUS 3Q Investor Call Highlights 2023 – Snippet 2
Byte ·
1 min read
ITUS 3Q Investor Call Highlights 2023 – Snippet 1
Byte ·
1 min read
ITUS 2Q Investor Call Highlights 2023 – Snippet 4
Byte ·
1 min read
ITUS 2Q Investor Call Highlights 2023 – Snippet 3
Byte ·
1 min read
ITUS 2Q Investor Call Highlights 2023 – Snippet 2
Byte ·
1 min read
ITUS 2Q Investor Call Highlights 2023 – Snippet 1
PMS & AIF Hub
Everything you need to understand how Portfolio Management Services and Alternative Investment Funds work.
Start here if you're evaluating a PMS or AIF for the first time
These articles are written for investors who want to understand — not just invest. No jargon without explanation.
Employee Stock Ownership Plans (ESOPs) have created extraordinary wealth for employees across some of the world’s most successful companies. For many professionals, ESOPs represent years of hard work and belief in the organisation’s growth. The challenge begins after that wealth is created. As ESOPs appreciate in value, they often become a disproportionately large part of an […]
Read MoreFor many US-based NRIs, the challenge isn’t gaining access to Indian equities—it’s finding an investment structure that works within the US tax framework. At Itus, our Category III AIF has been structured specifically with this objective in mind. At the fund level, the AIF has filed IRS Form 8832 to elect partnership status. Since a PFIC […]
Read MoreUnderstanding PFIC Rules and How Itus Category III AIF Offers a Better Alternative For most US-based NRIs, investing in India begins with the wrong question. “Which mutual fund should I invest in?” “Should I choose a PMS or an AIF?” The more important question is: How will the United States tax my Indian investments? This […]
Read MoreOCI cardholders enjoy broad access to Indian financial markets, but they are not treated identically to resident Indian investors for every regulatory and taxation purpose. The applicable investment process depends on factors such as tax residency, FEMA regulations and the chosen investment structure rather than OCI status alone. In most cases, OCI holders can invest […]
Read MoreNRIs can invest in India through either NRE or NRO bank accounts, depending on the source of funds and their repatriation requirements. An NRE account is generally used for income earned outside India and facilitates repatriation in accordance with applicable regulations. An NRO account is typically used for income arising within India, such as rent, […]
Read MoreAt Itus, the investment philosophy, research process and portfolio construction are identical across both our PMS and Category III AIF. Investors should therefore not expect one structure to outperform the other simply because of the investment vehicle. The decision is primarily driven by how you prefer to own the investment. A PMS is often suitable […]
Read MoreTax efficiency is not about paying the least amount of tax. It is about ensuring that the investment structure minimises unnecessary tax administration while allowing the investment strategy to be executed effectively. One of the key advantages of a Category III AIF is that taxation is administered at the fund level. The fund itself computes […]
Read MoreDifferent investment strategies require different investment structures. Category III AIFs are designed for strategies that actively manage listed market securities while providing a professionally governed pooled investment framework. For investors seeking exposure to actively managed public equity portfolios, this structure offers operational efficiency, consistency and a well-defined regulatory framework. Because all investors participate through a […]
Read MoreAt Itus, the investment philosophy, research process and portfolio construction remain the same whether you invest through our PMS or our Category III AIF. The difference lies not in what we invest in, but how the investment is structured and administered. In a PMS, investors own the underlying securities directly in their demat account. Every […]
Read MoreA PMS is designed to accommodate both additional investments and partial withdrawals, subject to the terms of the portfolio management agreement and regulatory requirements. Additional investments are typically deployed into the existing portfolio in line with the prevailing investment strategy and market conditions. Since markets are constantly evolving, the deployment may happen over a period […]
Read MoreIn a PMS, the investor is the legal owner of all securities and is therefore responsible for the taxes arising from investment activity. Unlike pooled investment products, where investors own units of a fund, a PMS operates through the investor’s own demat and bank accounts. Every purchase and sale is executed on behalf of the […]
Read MoreA PMS is not taxed as a separate entity. Since the securities are owned directly by the investor, taxation applies at the investor level in the same manner as direct equity investments. When securities are sold, any gains are classified as either short-term or long-term depending on the applicable holding period under the Income-tax Act. […]
Read More
PMS
How do PMS fee structures work, and why does Itus follow a hybrid (fixed + performance fee) model?
PMS providers generally follow one of three fee models—a fixed management fee, a performance-linked fee, or a combination of both. At Itus, we follow a hybrid structure because we believe investors should benefit from sustained wealth creation before the portfolio manager participates in the upside. Our fee structure consists of a fixed management fee of […]
Read MoreYes, in many cases existing listed shares can be transferred into a PMS instead of being sold and repurchased. Whether this is appropriate depends on the quality of the holdings, their tax implications and how well they fit within the investment strategy. One advantage of a PMS is that securities are held directly in the […]
Read More
